Quick Answer
Yes, a public adjuster can help Orlando homeowners, particularly when a claim is large, underpaid, delayed, or disputed. Public adjusters work exclusively for the policyholder, documenting damage, interpreting policy language, and negotiating with the insurance company to pursue a fairer settlement. Their value depends on whether the additional recovery outweighs their fee, which is capped by Florida law.
Why This Matters for Orlando Homeowners Right Now
It’s early November 2026, and Central Florida has just closed out another active hurricane season while moving into the drier, cooler months. For Orlando homeowners, this transition period is when storm-related damage surfaces: roofs that leaked quietly for weeks, attic mold that was masked by humidity, and drywall that finally shows staining as temperatures drop. If you filed a claim this fall and feel the payout fell short, or you’re staring at a denial letter as the new year approaches, now is the time to ask:does a public adjuster help with homeowners insurance in Orlando?
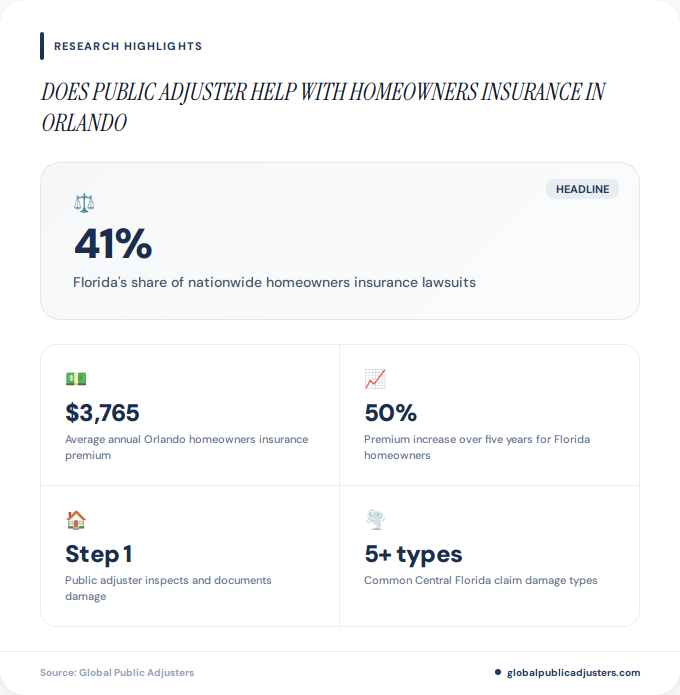
The answer matters more in Florida than almost anywhere else in the country. Florida representedunder 5% of national insurance claims but more than 41% of nationwide homeowners-insurance lawsuitsin 2025, a staggering imbalance that reflects how often claims here end up contested rather than resolved fairly the first time, according to reporting on Florida’s rising premiums and claims litigation trends.
What Does the Orlando Insurance Market Look Like in 2026?
Orlando homeowners are paying significantly more for coverage than they were five years ago, even though the city sits inland and avoids much of the direct hurricane-wind exposure that batters coastal communities. A 2026 estimate places the average Orlando homeowners premium at roughly$3,765 per year, or about $314 per month. Statewide figures vary by methodology: one 2026 source cites an average of$3,757including wind coverage, while another estimates$6,060 annuallyfor a home carrying $300,000 in dwelling coverage, according to NerdWallet’s Florida homeowners insurance analysis.
Homeowner sentiment reflects the strain. Nearly half of surveyed Florida homeowners reported premium increases of at least50% over five years, and almost three-quarters said their premiums continued to climb, per a Orlando Sentinel survey on Florida property insurance sentiment. A separate statewide poll found Floridians are now more concerned about insurance costs than property taxes, underscoring just how central this issue has become for homeowners from Winter Park to Lake Nona.
Orlando’s inland location does shift the type of damage homeowners typically face. Rather than direct hurricane-eyewall winds, Central Florida claims more often involvehurricane remnants, tornadoes spun off from tropical systems, severe thunderstorms, hail, plumbing failures, roof leaks, mold, and fire. It’s also worth remembering that standard homeowners policies generally exclude flood damage, so a separate flood policy may be necessary for properties near area lakes or in low-lying neighborhoods.
What Does a Public Adjuster Actually Do?
A licensed public adjuster represents the homeowner, not the insurance company, throughout the claims process. That distinction is the core of the service, and it’s why many Orlando homeowners bring one in after receiving a settlement offer that feels too low or a denial that seems disconnected from the actual damage.
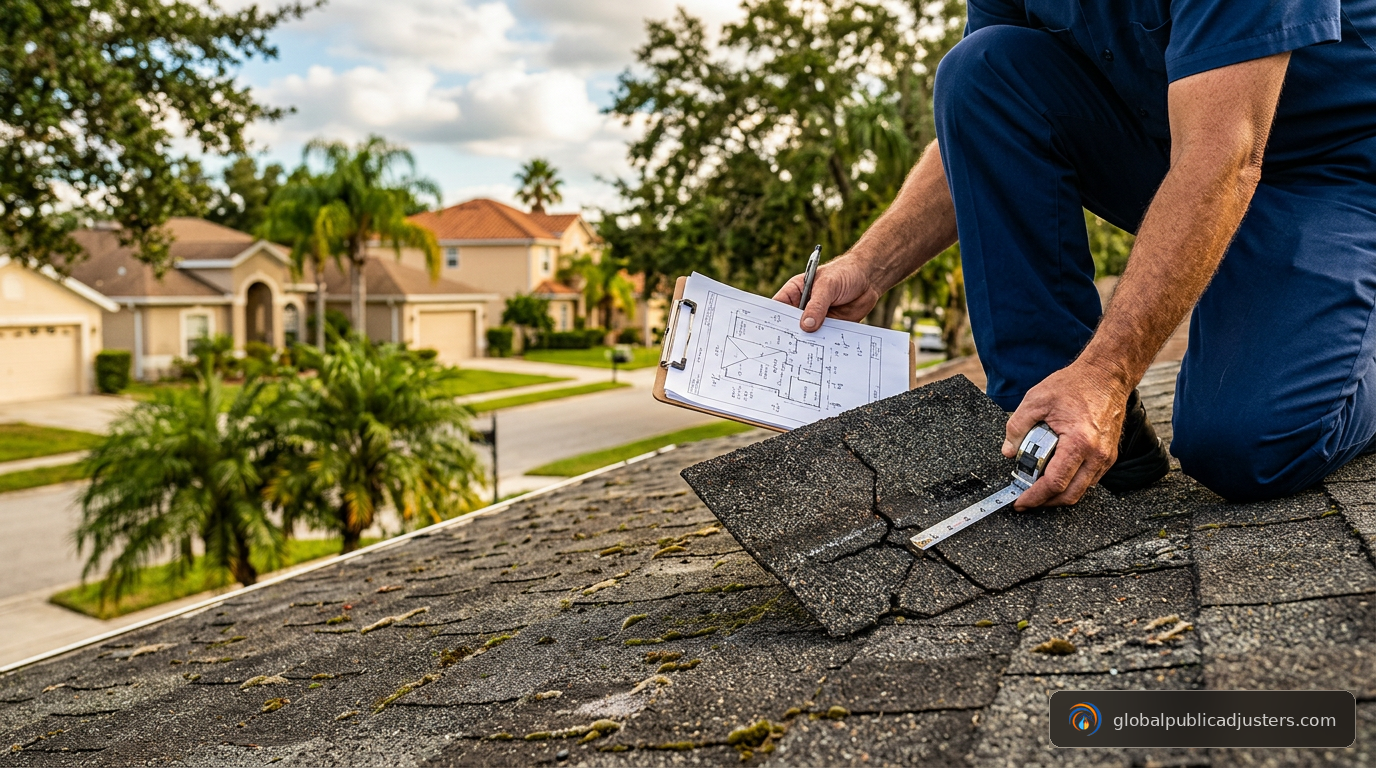
- Inspects and documents damage, including issues an initial adjuster may overlook, such as hidden roof decking damage or secondary water intrusion.
- Prepares a detailed repair or replacement-cost estimateusing line-item pricing comparable to what contractors and insurers use.
- Organizes supporting evidence, photographs, invoices, receipts, and personal property inventories needed for the proof of loss.
- Reviews policy languageacross dwelling, other structures, personal property, loss-of-use, ordinance-and-law, and additional-coverage provisions.
- Communicates directly with the insurerand its adjuster so the homeowner isn’t negotiating alone.
- Negotiates disputed issuesinvolving scope of damage, depreciation, causation, and valuation.
- Prepares supplemental or reopened claimswhen additional damage is discovered after the initial settlement.
For homeowners dealing with a specific claim type, resources like this guide togetting a fair water damage settlement in Orlandoor this overview ofpublic adjuster services for Florida homeownersbreak down the process in more detail.
“Homeowners often assume the insurance company’s adjuster is working on their behalf. In reality, that adjuster’s job is to protect the insurer’s bottom line. A public adjuster’s entire role is to level that playing field by documenting the loss the way the homeowner actually experienced it.”
When Should an Orlando Homeowner Hire One?
Not every claim needs a public adjuster. A straightforward, small claim with a cooperative insurer may resolve fine without one. But certain situations in Orlando consistently benefit from professional advocacy:
- The claim involves significant structural damage, such as roof failure, foundation issues, or widespread water intrusion.
- The insurer’s settlement offer seems far below the actual cost of repairs.
- The claim has beendenied outright or delayedfor weeks or months without clear explanation.
- Damage from a hurricane remnant or tropical storm event is disputed on causation grounds.
- Additional, hidden damage is discovered after the initial inspection (common with mold and water claims).
- The homeowner feels overwhelmed managing contractors, paperwork, and insurer communication simultaneously.
Homeowners in Jacksonville and Tampa face similar dynamics; see this breakdown ofwhat a public adjuster does and costs in Jacksonvilleor this2026 fee breakdown for Tampafor regional comparisons.
How Much Does a Public Adjuster Cost in Florida?
Florida law caps what public adjusters can charge, which protects homeowners from excessive fees. UnderFlorida Statute 626.854, compensation is generally limited as follows:
| Claim Type | Maximum Fee |
|---|---|
| Ordinary, non-emergency claims | Up to 20% of the claim payment or settlement |
| Claims tied to a declared emergency or state of emergency event | Up to 10% within the statutory window |
Pricing varies based on the complexity of the claim, the insurer involved, and the scope of documentation required, so exact fee structures should always be confirmed in writing before signing a contract. For a deeper look at how these percentages apply in practice, see this2026 pricing guide for Orlando homeowners. The Florida Department of Financial Services also maintains guidance on licensed insurance professionals and public adjuster regulations that homeowners can review before hiring anyone.
Public Adjuster vs. Insurance Company Adjuster: What’s the Difference?
| Factor | Public Adjuster | Insurer’s Adjuster |
|---|---|---|
| Who they work for | The homeowner | The insurance company |
| Compensation | Percentage of settlement, capped by Florida law | Salary from insurer |
| Primary goal | Maximize fair settlement for policyholder | Validate and manage insurer’s claim exposure |
This isn’t to say insurer adjusters act in bad faith by default, but their incentives differ fundamentally from the homeowner’s. The Florida Bar’s consumer resources on homeowners insurance rights and disputes echo this point, noting that policyholders are entitled to independent representation when navigating complex claims.
What Can’t a Public Adjuster Do?
It’s just as important to understand the limits of this service. A public adjuster cannot rewrite policy exclusions, force an insurer to pay a claim that genuinely isn’t covered, or guarantee a specific outcome. They also aren’t attorneys, so if a dispute escalates into litigation or requires legal interpretation of contract law, homeowners may need to involve a licensed attorney alongside their adjuster. Claims involving significant hurricane disputes, as seen inhurricane damage denials in Jacksonvilleorappeal strategies used in Tampa, sometimes require this combined approach.
Key Takeaways
- Public adjusters work exclusively for the homeowner, not the insurance company, when handling a claim.
- Florida law caps public adjuster fees at 20% for standard claims and 10% for emergency-declared events.
- Orlando’s average homeowners premium sits around $3,765 per year as of 2026, with statewide figures ranging higher depending on coverage.
- Florida accounted for over 41% of national homeowners insurance lawsuits in 2025 despite representing under 5% of claims nationally.
- Orlando homeowners face inland-specific risks like hurricane remnants, hail, plumbing failures, and mold rather than direct coastal wind damage.
- A public adjuster adds the most value on large, disputed, underpaid, or delayed claims, not minor or straightforward losses.
- Standard homeowners policies typically exclude flood damage, making separate flood coverage important for many Orlando properties.
People Also Ask
Is it worth hiring a public adjuster in Florida?
It’s typically worth it when a claim is large, complex, or already underpaid, since the additional recovery often exceeds the adjuster’s capped fee. For small, straightforward claims, the cost-benefit may not favor hiring one.
How much do public adjusters charge in Orlando?
Florida law generally caps fees at 20% of the settlement for ordinary claims and 10% for claims tied to a declared emergency event. Exact terms should be confirmed in writing before signing any contract.
What’s the difference between a public adjuster and the insurance company’s adjuster?
A public adjuster is hired by and represents the homeowner, while the insurer’s adjuster is employed by and represents the insurance company’s interests. Their incentives and loyalties differ fundamentally.
Can a public adjuster help with a denied claim?
Yes, public adjusters frequently review denied claims to identify documentation gaps, misapplied policy language, or undervalued damage that can support a supplemental or reopened claim. If the denial involves legal interpretation, an attorney may also be needed.
Frequently Asked Questions
Does a public adjuster really help with homeowners insurance in Orlando?+
Yes, especially for large, disputed, or underpaid claims where professional documentation and negotiation can meaningfully increase the settlement. For minor, uncontested claims, the benefit may be smaller.
What types of claims do Orlando public adjusters typically handle?+
Common Orlando claims include roof leaks, hurricane remnant and tornado damage, hail, plumbing failures, mold, and fire. Standard policies exclude flood damage, so flood claims require a separate policy entirely.
How long does a public adjuster claim take to resolve?+
Timelines vary widely depending on claim complexity, insurer responsiveness, and whether supplemental damage is discovered. Simple claims may resolve in weeks, while disputed or litigated claims can take several months.
Can a public adjuster guarantee my claim will be approved?+
No. A public adjuster cannot force an insurer to pay for damage excluded by the policy or guarantee a specific outcome. Their role is to document and advocate for the claim within the bounds of what the policy actually covers.
Why are Florida homeowners insurance premiums so high right now?+
Rising premiums reflect litigation volume, reinsurance costs, and storm risk, with nearly half of surveyed homeowners reporting at least a 50% increase over five years. Some counties have recently seen premium relief, though statewide costs remain elevated.
Do I need an attorney instead of a public adjuster?+
Not necessarily. A public adjuster handles documentation, estimates, and negotiation, while an attorney becomes necessary if the dispute requires litigation or legal interpretation of the policy contract. Many homeowners use a public adjuster first and only involve an attorney if the claim escalates.
If you’re facing a stalled, denied, or underpaid homeowners claim this fall, exploringinsurance claims support in Orlando, FLis a reasonable next step before the new year brings fresh maintenance and renewal deadlines. You can also reviewthe full range of claims services offered, learn moreabout the team behind the work, or browseclaim types handled across Florida. For homeowners ready to discuss a specific situation,reaching out for a claim reviewis the fastest way to find out whether professional representation makes sense. VisitGlobal Public Adjustersto start that conversation today.