Quick Answer
A water damage claim adjuster in Orlando, Florida either works for your insurance company to limit payouts or works as a licensed public adjuster representing you, the homeowner, to document damage and negotiate a fair settlement. Florida closed698,742 property-insurance claims in 2024, and water-related losses made up roughly24% of them, so understanding the difference between these two types of adjusters directly affects how much money you recover after a pipe burst, appliance leak, or storm-driven water intrusion.
Why Does Choosing the Right Adjuster Matter in Orlando?
Here’s a number that should give every Orlando homeowner pause: Florida closed698,742 property-insurance claims in 2024alone, with60,261 of those ending up in litigationand621,154 resolved without a lawsuit. That gap matters because the difference between a smooth payout and a courtroom fight often comes down to who is documenting and negotiating the claim from day one.
Awater damage claim adjuster in Floridaisn’t a single, neutral role. It’s actually two very different jobs wearing similar titles, and confusing them can cost homeowners thousands of dollars. This guide breaks down exactly what each type of adjuster does, when Orlando residents need professional representation, how the claims process unfolds, and what drives the cost of hiring help.
If you’re already dealing with standing water under your tile floors in Baldwin Park or a soaked drywall ceiling in Lake Nona, you may want to jump straight to our dedicated resource onwater damage claims in Orlandofor localized next steps.
What Is a Water Damage Claim Adjuster, and Who Do They Work For?
An insurance-company adjuster is hired, employed, or contracted by the insurer to investigate your claim. Their job includes inspecting the property, identifying the cause and date of loss, reviewing invoices and mitigation records, estimating repair costs, and determining whether exclusions, deductibles, or depreciation reduce your payout. They are professional, but their employer is the carrier, not you.
A public adjuster, by contrast, is licensed to represent the policyholder. Florida law, specificallyFlorida Statute 626.854, broadly defines public adjusting to include preparing, completing, or filing an insurance claim for compensation on the homeowner’s behalf. A public adjuster builds your scope of loss, documents contents and structural damage, and negotiates directly with the insurer’s adjuster.
“Homeowners often assume the adjuster who shows up at their door is working for them. In reality, that adjuster’s estimate reflects the carrier’s interests first. Having your own licensed representative levels the playing field during negotiation, not after a denial letter arrives.”
It’s worth repeating: a public adjuster cannot change your policy’s coverage terms or guarantee a specific payout. What they can do is make sure the damage is fully documented and fairly valued before the insurer finalizes its number.
When Do You Need a Public Adjuster for Water Damage in Orlando?
Not every leak requires a public adjuster. A small, clearly covered appliance malfunction with minor damage may settle quickly on its own. But several situations in Orlando consistently call for professional representation:
- Sudden and accidental losseslike burst pipes, water heater failures, or washing machine supply-line ruptures, especially when the insurer disputes the cause or timing.
- Storm-related water intrusionfollowing heavy rain events, where the carrier may argue the damage resulted from pre-existing wear rather than the storm.
- Claims involving mold growthsecondary to water damage, which insurers frequently try to limit or exclude. See our guide onmold damage services in Orlandofor how these claims are evaluated.
- Bathroom and kitchen leaksthat spread into subfloors, cabinetry, and adjacent rooms, often underestimated in initial carrier inspections. Ourbathroom damage services in Orlandopage covers common scope gaps in these claims.
- Low initial offersthat don’t reflect current Orlando-area labor and material costs for drying, demolition, and reconstruction.
- Supplemental damagediscovered mid-repair, such as rot or electrical damage hidden behind walls.
If any of these apply to your situation, reviewing a step-by-stepresidential damage claim process in Orlandocan help you understand what documentation you’ll need before the adjuster’s first visit.
How Does the Water Damage Claim Process Work, Start to Finish?
Understanding the sequence of events helps homeowners avoid costly mistakes in the first 72 hours after discovering water damage.
- Stop the source and mitigate.Shut off water, remove standing water, and begin drying to prevent mold. Most policies require reasonable mitigation efforts.
- Document everything.Photograph and video all affected areas, damaged contents, and the source of the leak before cleanup begins.
- Report the claim promptly.Delayed reporting is one of the most common reasons carriers scrutinize or deny claims.
- Insurer sends an adjuster.The company’s adjuster inspects, estimates, and determines whether the loss falls under a covered peril or an exclusion like flood or long-term maintenance neglect.
- Review the estimate carefully.Compare the carrier’s scope against actual repair costs from licensed contractors.
- Hire a public adjuster if needed.If the estimate seems low or coverage is disputed, a public adjuster can prepare a competing scope and proof of loss.
- Negotiate or file a supplemental claim.Additional damage found during repairs can be submitted even after the initial settlement.
Once repairs begin, many Orlando homeowners also need guidance on choosing a mitigation company. Our page onwater restoration services in Orlandoexplains how restoration documentation ties directly into claim valuation.
What Affects the Cost of Hiring a Public Adjuster?
Public adjuster fees in Florida are typically a percentage of the settlement, and that percentage can vary based on claim complexity, size of the loss, and whether the claim is a reopened or supplemental claim versus a new filing. Pricing varies based on your specific project, the scope of documentation required, and whether litigation becomes necessary.
Several factors influence overall cost and value delivered:
| Factor | Impact on Cost |
|---|---|
| Claim complexity | Disputed cause-of-loss or coverage disputes require more documentation and time. |
| Size of loss | Larger structural and contents losses require deeper inventory and estimating work. |
| Supplemental claims | Reopening a claim for newly discovered damage adds negotiation rounds. |
| Litigation risk | Claims headed toward the 60,261 litigated category statewide require more legal coordination. |
Actual repair and reconstruction costs for Orlando water damage can range widely, often from$5,000 to $75,000 or more, depending on the extent of structural damage, finishes involved, and whether mold remediation is required. We encourage homeowners to request a custom quote rather than rely on generic averages, since every property and loss is different.
How Do Public Adjusters Negotiate With Insurance Companies?
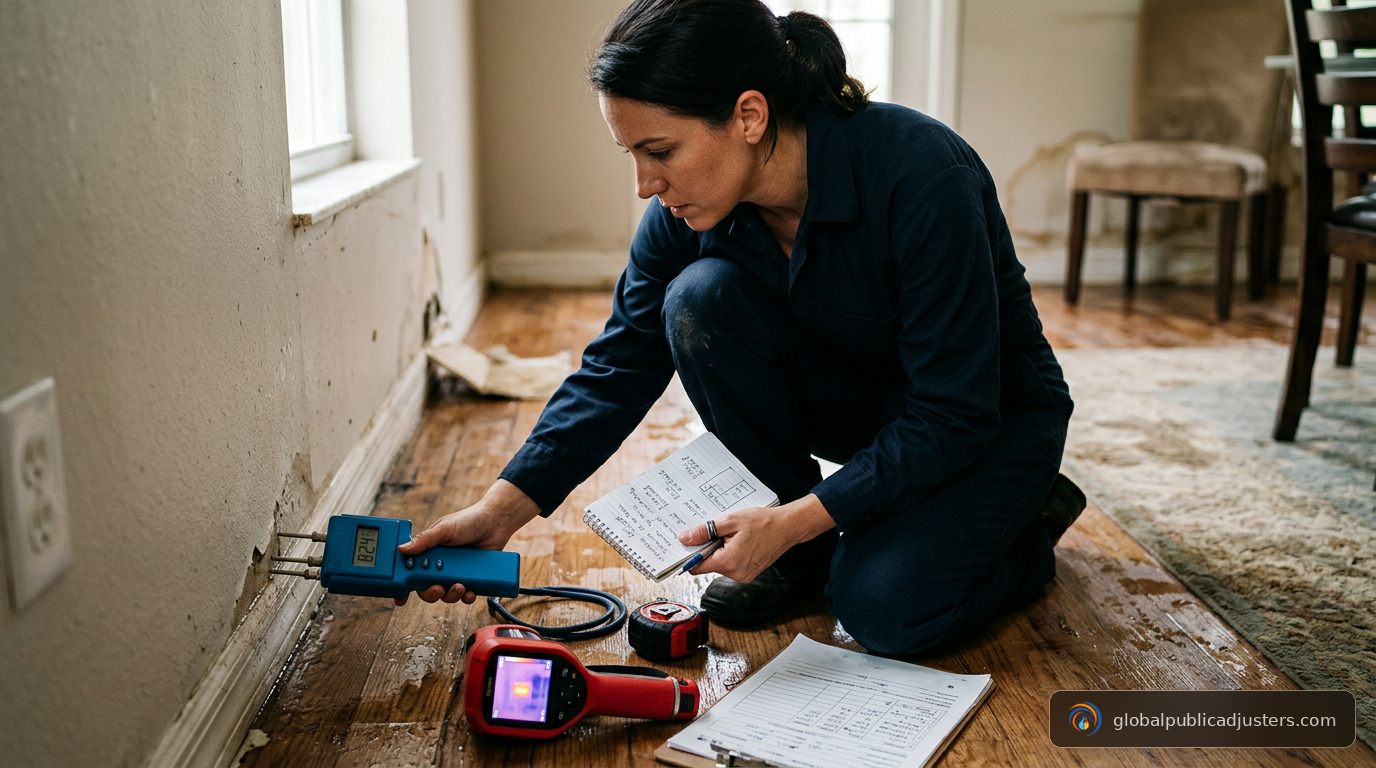
Negotiation starts long before a phone call with the carrier. A public adjuster builds a detailed, code-compliant scope of loss, backed by photos, moisture readings, contractor estimates, and sometimes expert reports. This documentation becomes the foundation for pushing back on a lowball offer.
Florida’s regulatory framework also plays a role. The Florida Department of Financial Services oversees licensed public adjuster conduct and contract requirements, which means adjusters must disclose compensation terms clearly and cannot guarantee outcomes. Separately, Florida Statute 626.8796 governs certain adjuster communications and conduct standards that apply during claim handling.
Public adjusters often identify underpaid line items the insurer’s adjuster missed, such as code-upgrade costs, matching requirements for flooring or cabinetry, and hidden moisture damage behind walls. For homeowners who also experienced roof-related water intrusion, our guide onpublic adjuster roof claim strategyoutlines similar negotiation tactics that apply to combined roof-and-water losses.
What Do Orlando’s Climate and Claims Data Tell Homeowners?
Orlando’s 2026 wet season has been notably active. Rainfall totals reached12 inches since April, roughly 18% above the seasonal average, according to local weather reporting. Heavy, sustained rainfall increases roof, window, drainage, slab, and stormwater-related claims, although insurers may still deny coverage for water entering through a pre-existing defect rather than storm force.
Statewide, water-related perils remain one of the largest claim categories. Florida recorded82,965 closed claimsfor “accidental discharge or overflow of water/steam” and another82,066 claimsclassified broadly as “other water,” together representing close to a quarter of all closed property claims reported by the state’scatastrophe and claims reporting data. A separate 2026 flood-risk analysis estimated about380,000 Florida propertiesface significant flood exposure, with average damage near$15,500per affected property.
Orlando homeowners should also be aware of the broader insurance climate. A recent survey found many Floridians remain skeptical that recent insurance reforms have improved claims outcomes, which underscores why documentation and professional representation matter more than ever when a claim is filed. For homeowners further along in the Florida claims pipeline, ourstep-by-step water damage claim guidewalks through documentation requirements that apply statewide, including in Orlando.
Litigated:60,261
Non-litigated:621,154
Other water:82,066
Combined share:~24%
Above average:~18%
People Also Ask
What’s the difference between a public adjuster and an insurance company adjuster?
An insurance company adjuster works for and is paid by the insurer to assess and often limit claim payouts. A public adjuster is licensed to represent the homeowner, documenting damage and negotiating for a fair settlement on the policyholder’s behalf.
Does homeowners insurance cover water damage in Florida?
Most Florida policies cover sudden and accidental water damage, such as burst pipes or appliance failures, but exclude gradual leaks, flood water, and damage caused by lack of maintenance. Flood damage typically requires separate flood insurance.
How long do I have to file a water damage claim in Florida?
Florida law sets statutory deadlines for reporting claims, but prompt reporting, ideally within days of discovering the damage, gives homeowners the strongest documentation and reduces disputes over cause and timing.
Can a public adjuster help if my water damage claim was denied?
Yes, a public adjuster can review the denial, re-examine the cause of loss, gather additional documentation, and file an appeal or supplemental claim challenging the insurer’s decision.
Is mold damage covered under a Florida water damage claim?
Mold coverage depends on the policy and whether the mold resulted directly from a covered water event versus long-term neglect. Many policies cap mold remediation coverage, so documentation of the original water source is critical.
Frequently Asked Questions
What should I do first after discovering water damage in my Orlando home?+
Stop the water source if possible, photograph the damage thoroughly, and begin reasonable mitigation like removing standing water. Then report the claim to your insurer promptly and consider consulting a public adjuster before accepting any settlement offer.
How much does hiring a public adjuster cost in Florida?+
Public adjuster compensation is typically a percentage of the final settlement and must be disclosed in a written contract per Florida law. Pricing varies based on claim complexity, size, and whether litigation becomes necessary, so it’s best to request a custom quote.
Can I negotiate directly with the insurance company’s adjuster myself?+
Yes, homeowners can negotiate directly, but insurer adjusters work for the carrier and may not flag every covered cost. Many Orlando homeowners hire a public adjuster specifically to level the documentation and negotiation playing field.
Does heavy Orlando rainfall increase my chances of a denied claim?+
Not necessarily, but insurers often scrutinize storm-related claims to determine whether damage resulted from the storm itself or a pre-existing defect. Thorough documentation at the time of the rain event strengthens your position.
What’s the difference between a covered water loss and an excluded flood loss?+
A covered water loss is typically sudden and accidental, like a burst pipe or failed appliance hose. Flood damage, caused by rising water from outside the home, is generally excluded from standard homeowners policies and requires separate flood insurance.
Can I file a supplemental claim after accepting an initial settlement?+
Yes, if additional damage is discovered during repairs that wasn’t part of the original estimate, you can typically file a supplemental claim. Keep all repair invoices and photos to support the additional request.
Key Takeaways
- Florida closed698,742 property claims in 2024, and water-related perils made up close to24%of that total statewide.
- An insurance company adjuster works for the insurer; a licensed public adjuster works for you, the homeowner.
- Orlando’s 2026 rainfall ran18% above average, increasing the likelihood of storm-related water claims across neighborhoods citywide.
- Public adjuster fees are contract-based and vary by claim complexity, never a flat statewide rate.
- Documentation, photos, invoices, and moisture readings, is the single biggest factor in a successful negotiation.
- Mold and supplemental damage often require additional claims beyond the initial settlement.
- Reviewing your policy’s flood versus water-damage definitions before a loss occurs can prevent coverage surprises.
Navigating a water damage claim in Orlando doesn’t have to mean accepting the first number an insurer offers. Whether you’re dealing with a burst pipe in Winter Park, storm intrusion in College Park, or a slow leak that turned into a mold problem near Dr. Phillips, professional representation can make a measurable difference in your settlement. Explore our full range ofpublic adjusting servicesor visit ourcontact pageto request a free claim review today. You can also learn more about our team on theabout us pageor start at theGlobal Public Adjusters homepageto see how we’ve helped Florida homeowners recover what they’re owed.