Quick Answer
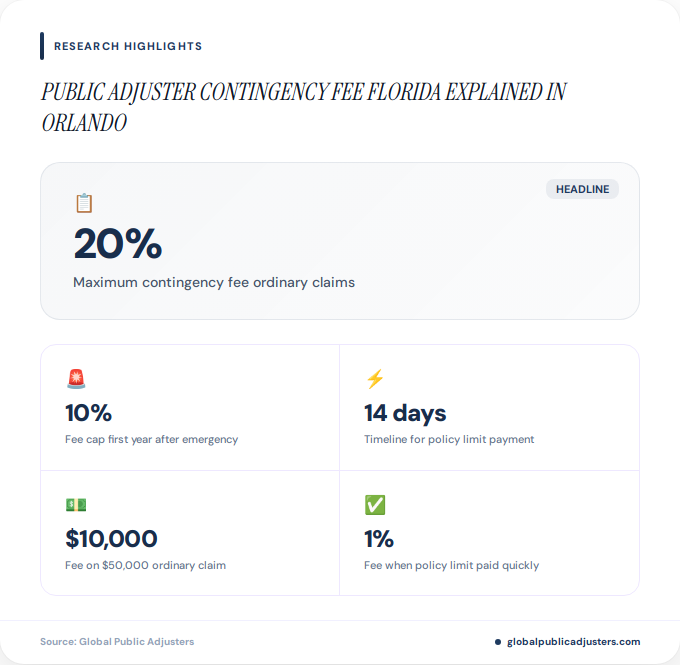
In Orlando, Florida law caps a public adjuster’s contingency fee at20% of the insurance paymentfor ordinary claims, dropping to10% during the first yearafter a Governor-declared state of emergency. The fee is owed only on money the adjuster actually helps recover, and your written contract must spell out exactly how and when it applies.
Here’s a number that surprises most Orlando policyholders: a public adjuster can legally charge20%of your insurance settlement, yet that same adjuster might recover two or three times more money than you would have gotten negotiating alone. Understanding thepublic adjuster contingency fee Floridarules, and how they’re explained in Orlando specifically, is the difference between feeling nervous about “giving up 20%” and recognizing it as a performance-based deal where you only pay when you win.
Florida regulates these fees tightly. The statutes set hard caps, define when lower caps apply, and specify what can and cannot be included in the calculation. This guide breaks down exactly what Orlando homeowners and business owners pay, why, and what legal protections exist if something feels off.
What Is a Public Adjuster Contingency Fee?
A contingency fee means the public adjuster’s payment is apercentage of the insurance money recovered for you, not an hourly rate or flat upfront charge. If no money is recovered, no fee is typically owed under a properly written contract. This model aligns the adjuster’s incentive directly with yours: the more they recover, the more both of you benefit.
This differs sharply from how insurance company adjusters are paid. Company adjusters work for the insurer and draw a salary regardless of claim outcome. A public adjuster, by contrast, works exclusively for the policyholder and is only compensated when they deliver results, a structure Florida’s Division of Consumer Services highlights in its public adjuster consumer tips guide.
What Are Florida’s Legal Fee Caps in 2026?
Florida Statute626.8698sets the controlling limits for public adjuster compensation statewide, including Orlando and the rest of Orange County. The general ceiling is20% of claim payments or settlements. But several exceptions change that number depending on timing and circumstances.
| Claim Situation | Maximum Fee |
|---|---|
| Ordinary residential or commercial claim | 20%of payments/settlements |
| Disaster claim, first year after Governor-declared emergency | 10% |
| Disaster claim, after the first year | 20% |
| Reopened or supplemental claim | 20%of the additional payment only |
| Policy limit paid very quickly (qualifying cases) | 1% |
That 1% rule is narrow but worth knowing. It can apply when the insurer pays, or agrees in writing to pay, the full applicable policy limit within14 days of the lossor within10 days after the public-adjuster contract is signed, whichever date comes later, as detailed underFlorida Statute 626.854governing public adjuster conduct and fee restrictions.
Also critical: a public adjustercannot charge a fee on money you already received before you signed the contract. On reopened or supplemental claims, the fee applies only to the new, additional payment, never to a prior settlement for the same cause of loss.
How Much Would an Orlando Homeowner Actually Pay?
Numbers make this concrete. Here’s how the caps play out on real claim sizes typical of Orlando-area roof, water, and storm damage claims:
- $50,000 ordinary claim at 20%:$10,000 fee; $40,000 remains before other deductions.
- $50,000 declared-disaster claim at 10%:$5,000 fee; $45,000 remains.
- $100,000 supplemental recovery at 20%:$20,000 fee, calculated only on the new recovery, not the original payment.
- $30,000 paid before hiring the adjuster, plus $20,000 recovered afterward:no fee on the prior $30,000; a 20% fee on the $20,000 recovered afterward equals $4,000.
- $200,000 claim against a $150,000 policy limit:a 20% fee on the full payment would be $40,000, subject to contract terms and statutory limits.
Pricing on any given Orlando claim varies based on your policy’s specific coverage, the extent of documented damage, and whether a Governor-declared emergency applies to your loss date. Rather than estimating from these examples alone, it’s worth getting acustom consultation for your specific claimbefore signing anything.
“Contingency doesn’t mean the adjuster works for free if the claim falls short. It means the fee structure rewards recovery. Policyholders should always confirm in writing whether the fee applies only to money actually recovered, whether expenses are billed separately, and what happens if they cancel the agreement early.”
What Does a Public Adjuster Do for That Fee?
A licensed public adjuster represents you, the policyholder, never the insurance company. For Orlando homes affected by summer thunderstorms, roof leaks, plumbing failures, or hurricane remnants moving through Central Florida, the scope of work typically includes:
- Inspecting and documenting building, contents, and business interruption losses.
- Preparing or reviewing the scope and valuation of damage, room by room.
- Interpreting policy language to identify coverage you may not realize you have.
- Building detailed claim inventories and repair estimates.
- Communicating directly with the insurer and its adjuster on your behalf.
- Negotiating the final claim amount before settlement.
One limitation worth stating plainly: a public adjuster generally cannot guarantee coverage or a specific payout. If a dispute escalates into a denial, bad-faith allegation, or litigation, that typically requires a Florida insurance attorney, either instead of or alongside the public adjuster. For claims that have already been denied, our guide onwhat to do next after a water damage claim denial in Orlandocovers that escalation path in detail.
What Consumer Protections Exist in Florida?
Florida built several safeguards into the public adjuster system specifically to prevent fee abuse. TheOffice of Program Policy Analysis and Government Accountability report on public adjustersdocuments the regulatory history behind these caps, including why lawmakers tightened rules after complaints about excessive post-disaster fees.
Cancellation terms:Must be spelled out
Applies to:Reopened and supplemental claims
Complaint process:Formal and documented
If you believe a fee or contract term violates these protections, Florida homeowners have a formal process to pursue it. Our companion piece onhow to file a complaint against a public adjuster in Floridawalks through that process step by step, even though it was written with a Tampa homeowner’s situation in mind, the statewide rules apply equally to Orlando residents.
When Does Hiring a Public Adjuster Make Sense in Orlando?
Orlando’s climate creates predictable claim triggers: summer afternoon storms that drive wind-blown rain into roofs, tropical systems tracking through Central Florida, and aging plumbing in neighborhoods like Baldwin Park, College Park, and Winter Park that leads to slow leaks and mold. Any of these scenarios can justify bringing in a public adjuster, particularly when:
- The insurer’s initial offer seems low relative to visible or suspected damage.
- Your claim involves multiple categories of loss (structure, contents, additional living expenses).
- You’re unsure how to interpret complex policy exclusions or endorsements.
- A previous settlement left out documented damage, making a supplemental claim appropriate.
- You simply don’t have the time to manage inspections, paperwork, and insurer calls yourself.
For a broader look at whether this service fits your specific homeowners policy situation, seedoes a public adjuster help with homeowners insurance in Orlando. Water intrusion claims in particular benefit from careful early documentation, a process outlined in ourFlorida water damage claim documentation guide.
How Do You Choose the Right Public Adjuster?
Not every contingency contract is written the same way, and the percentage isn’t the only term that matters. Before signing, confirm the following in writing:
- Is the fee based strictly on amounts recovered after the contract date?
- Are expenses (inspections, estimators, experts) billed separately or included in the percentage?
- What happens to the fee obligation if you terminate the contract early?
- Is the adjuster licensed in Florida, and in good standing with the Department of Financial Services?
- Does the contract match the statutory caps exactly, with no hidden add-on charges?
A thorough breakdown of typical fee structures and how they compare market to market is available in our2026 public adjuster fee breakdown for Tampa, which mirrors the same statutory framework that applies in Orlando. For a full view of available services, visit ourpublic adjuster services pageor review specificclaim types we handle.
Key Takeaways
- Florida caps ordinary public adjuster contingency fees at20%of the insurance payment recovered.
- Claims tied to a Governor-declared disaster are capped at10%during the first year after declaration.
- A rare1% capapplies when the full policy limit is paid within 14 days of loss or 10 days of contract signing.
- Adjusters cannot charge fees on money paidbeforeyou signed the contract.
- Supplemental and reopened claims are billed only on thenew money recovered, not prior settlements.
- Always get the fee structure, expense terms, and cancellation policy in writing before signing.
- Orlando’s storm and water-damage claim patterns make understanding these caps especially relevant for local homeowners.
People Also Ask
Is 20% a normal public adjuster fee in Florida?
Yes, 20% is the standard statutory maximum for ordinary residential and commercial claims in Florida, including Orlando. Lower caps apply for disaster-related claims within the first year of a Governor-declared emergency.
Do public adjusters get paid if the claim is denied?
Under a standard contingency contract, if no money is recovered, no fee is typically owed. However, contract terms vary, so it’s important to confirm in writing what happens with expenses or partial recoveries.
Can a public adjuster charge on money already paid before they were hired?
No. Florida law prohibits charging a fee on insurance payments received before the public-adjuster contract was signed. This protects policyholders who received a partial payment before deciding to hire help.
What makes a claim count as a “disaster claim” with a 10% cap?
A claim qualifies for the 10% cap when it arises from a loss covered by a Governor-declared state of emergency, and only during the first year following that declaration. After one year passes, the standard 20% cap applies again.
Frequently Asked Questions
How is a public adjuster contingency fee calculated in Orlando?+
The fee is a percentage, up to 20% in ordinary cases, applied to the actual insurance payment or settlement recovered. It excludes money paid before the contract was signed and, for supplemental claims, excludes any prior settlement for the same loss.
Does the 10% disaster cap apply to all Orlando storm claims?+
Only claims tied to a loss that falls within a Governor-declared state of emergency, and only within the first year after that declaration, qualify for the 10% cap. Routine wind or water damage outside a declared emergency period is subject to the standard 20% cap.
Can a public adjuster charge extra fees beyond the contingency percentage?+
Reputable public adjusters typically do not add separate charges beyond the agreed percentage, but contract terms vary. Always confirm in writing whether expenses like inspections or expert reports are included in the fee or billed separately.
What is the 1% fee rule and when does it apply?+
The 1% cap applies narrowly, when the insurer pays or agrees in writing to pay the full applicable policy limit within 14 days of the loss or 10 days after the public-adjuster contract is signed, whichever is later. It’s uncommon but legally protected for qualifying rapid settlements.
Is hiring a public adjuster worth the fee in Orlando?+
Many policyholders find that a public adjuster’s negotiation and documentation work results in a significantly higher settlement than they would have received alone, even after the fee. Value depends on claim complexity, so it’s worth discussing your specific situation before deciding.
What should be in a public adjuster contract before I sign?+
The contract should clearly state the fee percentage, confirm it applies only to money actually recovered after signing, disclose whether expenses are separate, and explain cancellation terms. Comparing this to guidance from the Orlando public adjuster resources can help you spot standard versus unusual terms.
Where can I verify Florida’s public adjuster fee statutes myself?+
You can review the governing law directly through the Florida Legislature’s statute database, including the specific section covering public adjuster contracts and compensation under Florida Statute 626.8698 on the state legislature’s site.
Understanding thepublic adjuster contingency fee Floridaframework gives Orlando policyholders real leverage before they sign anything. The caps exist to protect you, but only if you know they’re there and insist your contract reflects them precisely. If you’re weighing a claim and want clarity on what a licensed, Florida-compliant contingency agreement should look like for your specific situation,reach out to our team for a free claim review, or learn more about our approach on theAbout Us page. For a broader view of how we support Florida homeowners from first inspection to final settlement, visitGlobal Public Adjustersdirectly.