Quick Answer
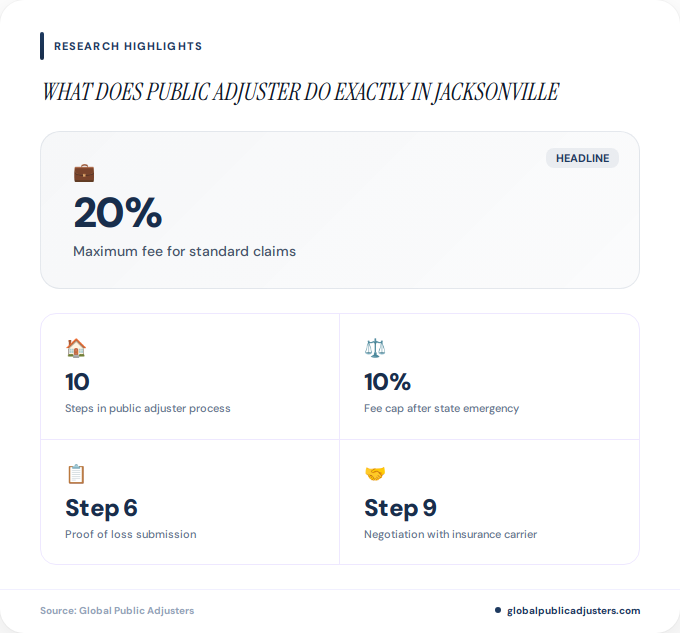
A public adjuster in Jacksonville inspects property damage, interprets your policy, documents and values your loss, prepares the proof of loss, and negotiates directly with your insurance company on your behalf. Florida law caps their fee at20% of the claim paymentfor standard claims and10% during the first year after a declared state of emergency. Pricing within those legal limits still varies based on claim complexity, property type, and the scope of damage involved.
What Is a Public Adjuster in Jacksonville?
Here’s a number that surprises most homeowners: Florida law allows a licensed public adjuster to collect up to20% of your claim payment, yet that same statute also limits what they can charge, when they can charge it, and what paperwork they must give you first. Understanding what does a public adjuster do exactly in Jacksonville starts with one core fact: they work for you, the policyholder, not for the insurance carrier.
A public adjuster is a state-licensed professional who investigates, documents, and negotiates property insurance claims on behalf of homeowners and business owners. In Jacksonville, where coastal humidity, aging roofs, and hurricane season converge, that representation often determines whether a claim is paid fairly or underpaid. Unlike the adjuster your insurance company sends out, a public adjuster has a legal and contractual obligation to maximize your recovery, not the insurer’s.
For a broader breakdown of representation rights and limits, seewhat a public adjuster can do for youbefore filing your next claim.
What Does a Public Adjuster Actually Do, Step by Step?
The day-to-day work of a Jacksonville public adjuster covers far more than taking photos of a leaky roof. It is a structured process that mirrors (and often exceeds) the depth of the insurer’s own investigation.
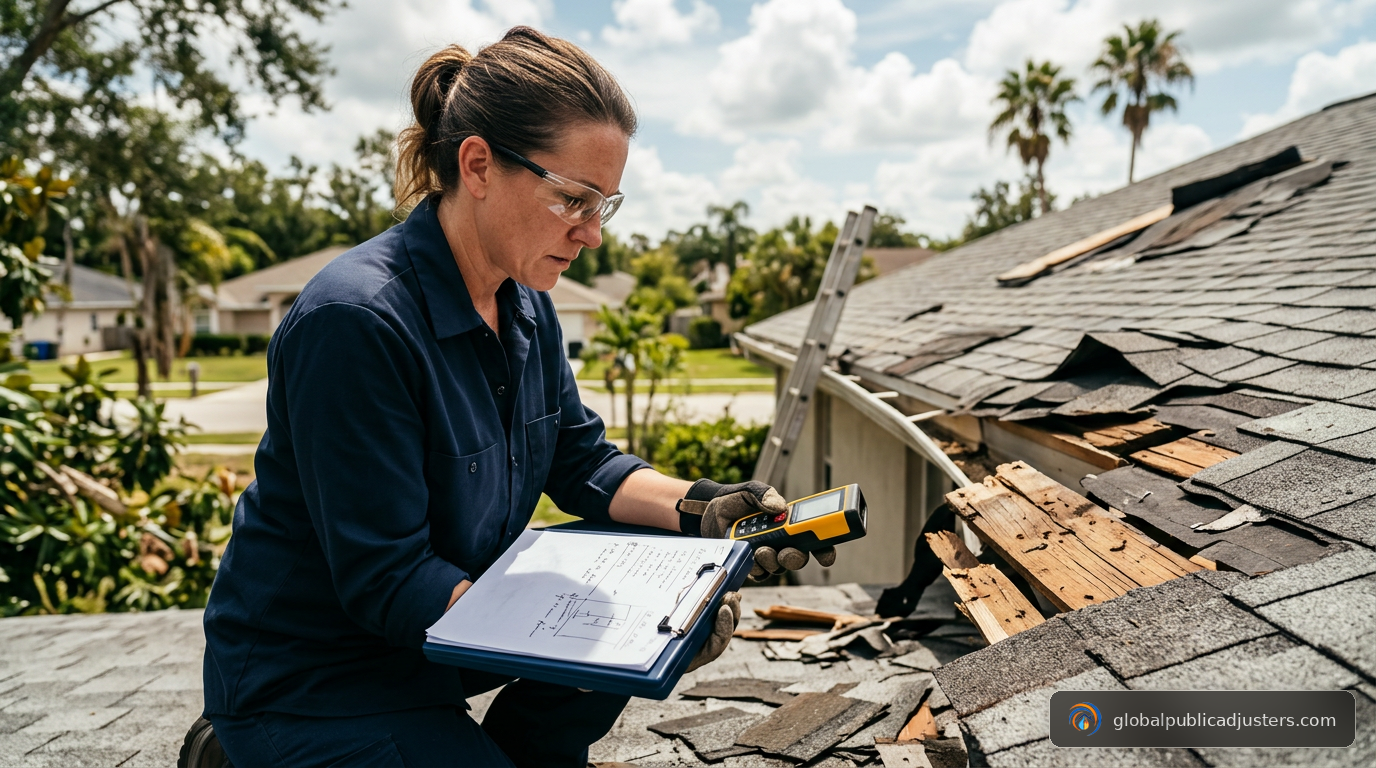
- Property inspection:A full walkthrough covering roof, water intrusion, wind and hurricane damage, fire, mold, structural components, contents, and business-interruption losses.
- Damage documentation:Photographing and measuring damage, including issues the insurer’s initial inspector may have missed or underestimated.
- Policy review:Reading the declarations page, exclusions, deductibles, endorsements, coverage limits, and loss conditions line by line.
- Inventory preparation:Cataloging damaged personal property and building components in detail.
- Estimate development:Building a repair or replacement estimate using construction pricing software and a clear scope of work.
- Proof of loss submission:Preparing and filing the formal proof of loss with supporting documentation.
- Insurer communication:Coordinating with the carrier’s adjuster, engineers, and consultants throughout the claim.
- Supplemental claims:Identifying additional damage discovered after the first payment, which happens frequently with water and hurricane losses.
- Negotiation:Pushing back on lowball offers and negotiating the final settlement amount.
- Deadline tracking:Monitoring payment timelines, depreciation holdbacks, deductible application, and any unresolved coverage disputes.
Importantly, a public adjusterdoes not work for the insurer, cannot guarantee a coverage outcome, and generally cannot give legal advice or represent you in court. If your claim involves a flat denial or a serious coverage dispute, you may need an insurance attorney in addition to, or instead of, a public adjuster. For situations involving a denied claim, review this guide on ahurricane damage claim denial in Jacksonvillefor next steps.
How Much Does a Public Adjuster Cost in Jacksonville?
Public adjuster fees in Florida are not negotiable above the statutory ceiling, but the actual percentage charged within that ceiling can vary by firm, claim complexity, and timing. Costs generally fall into a few ranges depending on the type of claim.
| Claim Type | Maximum Fee |
|---|---|
| Ordinary, non-emergency claim | Up to 20% of claim payments |
| Claim tied to a declared state of emergency (first year) | Up to 10% |
| Same emergency claim, after the first year | Up to 20% |
| Claims the insurer pays quickly at or near policy limits | Up to 1% of the applicable coverage part |
These caps are set under Florida law and apply specifically toFlorida Statute 626.854 governing public adjuster compensation. The percentage is calculated only on the portion of the payment obtained through the adjuster’s work, not the entire policy limit, and excludes any separate attorney fees or costs, according to the Florida Insurance Consumer Advocate’s public adjuster guidance.
Pricing varies based on your specific project, the type of damage, and whether the claim is contested. For a deeper breakdown by claim size and region, see this2026 public adjuster pricing guide for Florida homeowners, or compare notes withTampa’s 2026 fee breakdownfor a regional cost comparison.
What Factors Affect the Final Cost?
No two claims cost the same amount to adjust, even under the same fee cap. Several variables shape the final number a Jacksonville homeowner will see.
Single-issue claims:Lower scope
Standard claims:20% cap
Commercial/business-interruption:Expanded scope
Disputed/denied claim:More involved
Florida’s insurance market has shifted recently, with Jacksonville-area homeowners seeing property insurance costs decline after years of increases, which has also affected how carriers staff and respond to claims. Fewer premium increases don’t necessarily mean faster or fairer claim payments, which is exactly where a public adjuster’s documentation and negotiation work adds measurable value. Always request a custom quote and written contract before work begins, since Florida requires a signed agreement before any fee can be collected from policyholder payments.
How Is a Public Adjuster Different From the Insurance Company’s Adjuster?
This is one of the most common points of confusion for Jacksonville homeowners filing their first claim. The insurance company’s adjuster, sometimes called a staff or independent adjuster, is paid by and represents the carrier. A public adjuster is hired and paid by the policyholder, and their entire role is to counterbalance that relationship.
- Who they represent:Insurer’s adjuster represents the carrier; public adjuster represents the homeowner.
- Who pays them:Insurer’s adjuster is salaried by the company; public adjuster earns a percentage fee capped by state law.
- Incentive structure:Insurer’s adjuster has no financial stake in a higher payout; public adjuster’s fee rises only if your settlement increases.
- Scope of estimate:Insurer’s adjuster may scope conservatively; public adjuster documents the full extent of covered damage.
Recent industry reporting has highlighted growing scrutiny of public adjuster practices nationally, including regulatory attention on claims handling standards covered by Claims Journal, which underscores why choosing a licensed, transparent firm with a clear written contract matters. If your claim was already denied by the carrier’s own adjuster, this resource on adenied water damage claim in Floridaoutlines the appeal pathway.
When Should a Jacksonville Homeowner Hire One?
Not every claim needs a public adjuster, but several situations make hiring one worthwhile. Hurricane season damage across the Riverside, Mandarin, Arlington, and Southside areas of Jacksonville often involves layered roof, water, and wind damage that’s easy for an initial inspection to undervalue. Older homes near the Jacksonville waterfront and downtown core also tend to have complex construction details that benefit from a detailed line-item estimate.
- Your claim involves significant structural, roof, or water damage.
- The insurer’s initial offer seems far below your repair estimates.
- You’re unsure how to interpret policy exclusions, endorsements, or depreciation schedules.
- You’ve discovered supplemental damage after the first payment was issued.
- Your claim has gone unresolved for weeks or months without clear communication.
Homeowners dealing with a denied hurricane claim can review strategies in this guide onwhy hurricane claims get rejected and how to appeal, while water-damage-specific claims are covered inhow to get a fair water damage settlement in Florida. For a full look at available representation options, visitGlobal Public Adjusters’ service offeringsor learn moreabout the firm’s claims experience.
Florida’s Contract and Timeline Requirements
Florida requires a written contract before a public adjuster can collect any fee from payments made to the policyholder, and that contract must be signed and copied to both the homeowner and the insurer. State guidance also requires the adjuster to deliver a written damage estimate for the proof of loss within60 days of signing the contract, according to the state’s public adjuster consumer tips document. Homeowners can also review dispute resolution options through theJacksonville Value Adjustment Boardfor property-related disputes outside the insurance claim process itself.
Key Takeaways
- A Jacksonville public adjuster represents the policyholder, inspecting, documenting, and negotiating claims entirely on the homeowner’s behalf.
- Florida law caps fees at20% of claim paymentsfor standard claims and10% during the first yearafter a declared state of emergency.
- A signed written contract is required before any fee can be collected, and a damage estimate must be submitted within 60 days of signing.
- Public adjusters cannot guarantee coverage outcomes or provide legal representation; disputed denials may require an insurance attorney.
- Costs vary based on claim complexity, property type, and whether the loss is tied to a declared emergency.
- Supplemental damage found after the first payment is common, especially with hurricane and water claims, and should be reported promptly.
- Always request a custom quote and review the contract terms carefully before signing with any public adjuster firm.
People Also Ask
What exactly does a public claims adjuster do?
A public claims adjuster inspects property damage, reviews the insurance policy, prepares a detailed repair estimate, files the proof of loss, and negotiates the settlement with the insurance company entirely on behalf of the policyholder.
Is hiring a public adjuster worth it in Jacksonville?
It depends on claim size and complexity. For significant hurricane, water, or structural damage claims where the insurer’s offer seems low, a public adjuster’s documentation and negotiation often results in a higher, more accurate settlement than homeowners can achieve alone.
How many public adjusters work in the Jacksonville area?
Jacksonville has a growing number of licensed public adjusters and firms, reflecting steady demand tied to hurricane season claims, roof damage, and water intrusion issues common to Florida’s coastal climate.
Can a public adjuster guarantee my claim will be approved?
No. A public adjuster cannot guarantee coverage or approval; they can only document, support, and negotiate the claim based on the policy’s actual terms and the extent of covered damage found.
Frequently Asked Questions
What does a public adjuster do exactly in Jacksonville?+
A Jacksonville public adjuster inspects property damage, interprets the insurance policy, documents and values the loss, prepares the proof of loss, and negotiates directly with the insurer. They represent the policyholder exclusively, not the insurance company.
How much does a public adjuster cost in Jacksonville?+
Florida law caps public adjuster fees at 20% of claim payments for ordinary claims and 10% during the first year following a declared state of emergency. Actual pricing within those caps varies based on claim complexity and scope.
Can a public adjuster represent me in a lawsuit against my insurer?+
No. A public adjuster generally cannot provide legal advice or represent you in court. If your claim involves a serious coverage dispute or denial, an insurance attorney may be needed alongside or instead of a public adjuster.
Do I need a written contract before hiring a public adjuster in Florida?+
Yes. Florida requires a signed written contract before a public adjuster can collect fees from policyholder payments, and a copy must be provided to both the homeowner and the insurance company.
What is the difference between a public adjuster and the insurance company’s adjuster?+
The insurance company’s adjuster is paid by and represents the carrier. A public adjuster is hired and paid by the homeowner, earning a percentage fee only if the claim settlement increases, aligning their incentive with the policyholder.
How long does a Jacksonville public adjuster take to settle a claim?+
Timelines vary by claim complexity, but Florida requires the adjuster to deliver a written damage estimate for the proof of loss within 60 days of signing the contract. Negotiation and final settlement can take longer depending on the insurer’s response.
Can I hire a public adjuster after my claim has already been denied?+
Yes. Public adjusters frequently assist homeowners after an initial denial by re-documenting the loss, identifying overlooked damage, and preparing a stronger supplemental claim or appeal for the insurer’s review.
Understanding what does a public adjuster do exactly in Jacksonville is the first step toward protecting your claim from underpayment. Whether you’re dealing with hurricane damage, a slow-moving water claim, or a denial you believe was unfair,Global Public Adjusterscan review your policy and provide a custom quote based on your specific situation. Visit thecontact pageto discuss your claim with a licensed professional, or browseclaim types handledto see if your situation qualifies for representation.