Do I need a public adjuster for a hurricane and wind claim in Pensacola?
It helps most when the damage is large, the claim is complicated, or the insurer's offer seems low. A licensed public adjuster from our Pensacola office on East 9 Mile Road documents your hurricane and wind damage, reviews your policy and negotiates for you, with no upfront cost.
Does homeowners insurance cover hurricane damage in Pensacola?
Usually yes for wind damage. Most Florida homeowners policies cover hurricane wind damage to the roof, structure and belongings, after a separate hurricane deductible, often 2% or 5% of dwelling coverage. Flooding and storm surge are excluded and need a separate flood policy.
What we see in Pensacola hurricane and wind claims
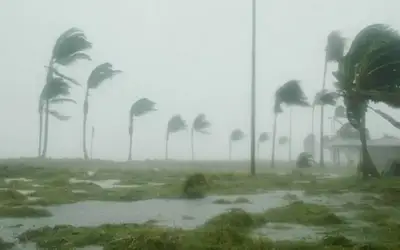
Pensacola knows hurricanes: Ivan devastated the area in 2004, and Sally flooded downtown and damaged thousands of homes in 2020. Our Pensacola office on East 9 Mile Road is helping Panhandle property owners with storm claims right now, from roof and wind damage to water intrusion.
Local office: 312 E 9 Mile Rd, Suite 29D, Pensacola, FL 32514. Call 407-900-5025.
Storms and risks in Escambia County
Escambia County has been hit by major storms including Ivan in 2004 and Sally in 2020, which flooded downtown Pensacola. The Panhandle is in an active storm period again.
Signs of hurricane and wind damage to document
- Missing or lifted shingles, tiles or flashing
- Water stains on ceilings and walls after the storm
- Broken windows, doors, soffits, fascia or screen enclosures
- Fallen trees or limbs on the structure
- Damaged fences, carports and outbuildings
What to do right now
Photograph everything before cleanup, make temporary repairs to stop more damage, and keep every receipt. Report the claim promptly: Florida generally allows 1 year from the date of loss for a new claim.
How we handle Pensacola hurricane and wind claims
- Free claim evaluation. Call or use the form. We review your damage, policy and claim status.
- Inspection and documentation. Photos, measurements and a line-by-line repair estimate.
- Claim preparation. We present the claim and meet your insurer's adjuster on site.
- Negotiation and settlement. We push back on low offers with evidence. You approve the final number.
How much does a public adjuster cost in Pensacola?
Nothing upfront. Florida public adjusters are paid a percentage of the settlement, and section 626.854 caps it at 10% for claims from a declared state of emergency during the first year and 20% otherwise. The fee must appear in bold in your contract.
How long do I have to file a hurricane and wind claim in Florida?
Under section 627.70132, Florida Statutes, you generally have 1 year from the date of loss to report a new or reopened property claim and 18 months to file a supplemental claim. The clock starts when the damage happened, not when you noticed it.
Can you reopen a denied or underpaid hurricane and wind claim in Pensacola?
Often, yes. We review the denial letter or settlement, your policy and the property, then document what the insurer missed. If you're within Florida's notice deadlines and the evidence supports it, we reopen or supplement the claim and negotiate for the full amount owed.